
Using a credit card for your Buy Now, Pay Later (BNPL) purchases can help you manage your expenses and earn rewards. But not all credit cards will work with all BNPL services, and interest rates or extra fees can quickly add to your costs.
In this guide, I’ll go over the best credit cards for Buy Now, Pay Later users in the USA by comparing rewards, annual fees, payment flexibility, and key benefits to help you find an option that suits your spending habits and financial objectives.
How to Choose the Right Credit Card for BNPL Purchases?
Compare Interest Rates: Look for a credit card that has a low APR or introductory 0% APR offer to make larger purchases more affordable and reduce your borrowing costs.
Review Annual Fees: Balance the annual fees with potential rewards and benefits. For the occasional shopper, a no-annual-fee card might be the best option, but frequent spenders could be attracted to premium features.
Investigate Rewards Programs: Choose a card that offers cash back, points or rewards for your everyday purchases. You can derive value from these benefits when you responsibly pay your credit card bills.
Verify BNPL Compatibility: Ensure your credit card is compatible with your preferred BNPL option. Some services are restricted to credit card repayments or charge additional transaction fees.
Look at Repayment Options: Look for cards that offer qualifying installment plans or promotional financing. Select a payment option based on the repayment periods, interest charges and applicable fees.
Verify Credit Score Requirements: Research the usual credit score needed for each card before applying. Picking the right card can improve approval odds and avoid unnecessary hard inquiries.
Compare Fees and Penalties – Compare late-payment fees, balance transfer fees, and other charges Knowing these words can help you avoid surprise charges when you’re making multiple purchases or installment payments.
Think About the Credit Score Impact: Choose a card that promotes responsible credit use. Maintain low utilization, pay your bills on time, and don’t overborrow to protect your credit profile.
Tips for Managing Credit Card and BNPL Payments
Budget Monthly: Develop a realistic budget that includes essential expenses, credit card bills, and BNPL installments. Only borrow what you are comfortable repaying and not endangering your financial security.
Record all payment due dates: Maintain a calendar of all your credit card bills and BNPL instalment due dates. Set reminders to avoid missed payments, late fees and needless financial stress.
Don’t Overdo BNPL Installments: Don’t have too many BNPL plans running at once so you don’t end up paying at the same time. Too many installments can strain your monthly budget and be difficult to pay back.
Pay Credit Card Bills on Time: Pay at least the minimum payment on or before the due date. Pay your statement balance in full to avoid paying interest on eligible purchases.
Track Your Spending Regularly: Check your credit card transactions and BNPL balances weekly. Watch your purchases so you can see overspending early and keep upcoming payments manageable within your budget.
Know the fees and interest: Read the terms of all credit cards and BNPL plans carefully. Check interest rates, late fees, installment charges and conditions for promotional offers before buying.
Keep your credit utilization low: Don’t carry large balances on your credit cards compared to the amount of credit you have available. Lower utilization and timely payments could help a better credit profile over time.
Create An Emergency Fund Set aside funds for unexpected expenses so that emergencies do not disrupt scheduled repayments. Having a financial cushion means you have room to handle installments without having to borrow more.
Key Points
| Credit Card | Issuer | BNPL Feature | Key Point |
|---|---|---|---|
| Chase Sapphire Preferred® Card | Chase | Chase Pay Over Time | Allows eligible purchases to be split into fixed monthly payments while still earning travel rewards |
| Chase Freedom Unlimited® | Chase | Chase Pay Over Time | Flexible installment plans on eligible purchases combined with strong cash back earning rates. |
| Chase Freedom Flex® | Chase | Chase Pay Over Time | Offers fixed-payment financing plans for qualifying purchases and rotating bonus categories. |
| Citi Double Cash® Card | Citi | Citi Flex Pay | Converts eligible purchases into predictable monthly payments while continuing to earn cash back rewards. |
| Citi Custom Cash® Card | Citi | Citi Flex Pay | BNPL flexibility paired with automatic bonus rewards in top spending categories. |
| Citi Strata Premier℠ Card | Citi | Citi Flex Pay | Suitable for larger travel and everyday purchases that can be repaid through installment plans. |
| American Express® Gold Card | American Express | Plan It® | Lets cardholders split eligible purchases into fixed monthly payments while earning Membership Rewards points. |
| The Platinum Card® from American Express | American Express | Plan It® | Premium rewards card with installment-payment options for expensive purchases. |
| Blue Cash Preferred® Card from American Express | American Express | Plan It® | Combines strong everyday cash back categories with pay-over-time flexibility. |
| U.S. Bank Altitude® Go Visa Signature® Card | U.S. Bank | ExtendPay® | Enables eligible purchases to be repaid in installments while earning rewards on daily spending |
1. Chase Sapphire Preferred Card®
The Chase Sapphire Preferred® Card is a popular travel rewards card that also offers a Buy Now, Pay Later option through Chase Pay Over Time. Splitting eligible purchases into fixed monthly payments makes it easier to budget for big expenses. Cardholders get the best of both worlds: payment flexibility and valuable travel and dining rewards.
It does have an annual fee, but it provides good overall value for frequent travelers. Applicants usually must have good to excellent credit. Revolving balances are subject to the standard APR, but BNPL plans have a fixed payment plan. Late payments can lead to fees and damage credit scores and future borrowing ability.
Key Features
- Travel Rewards: Earns extra points on eligible travel bookings, dining, online groceries, streaming, gas, and EV charging.
- Flexible redemption options for eligible travel and other rewards
- Travel Protections: Provides eligible coverage for trip cancelation, interruption and rental car.
- Travel Credit: Enjoy an annual credit on your hotel statement when you make eligible bookings via Chase Travel.
- No Foreign Transaction Fees Good to Know for Eligible Purchases When Traveling Abroad
Key Limitations
- Annual Fee: Has a $95 annual fee.
- No Standard Introductory Purchase APR: Typically, purchases are not eligible for a standard intro 0% APR offer.
- Rewards Restrictions: Certain purchases and transactions may not qualify for bonus points.
- BNPL Restrictions: Compatibility will depend on the provider, merchant and transaction type.
2. Chase Freedom® Unlimited
Chase Freedom Unlimited® gives you everyday cash back rewards and Chase Pay Over Time functionality. Users receive cash back rewards on purchases and are able to split eligible transactions into affordable monthly payments. A card with no annual fee is attractive to those keeping an eye on their budgets.
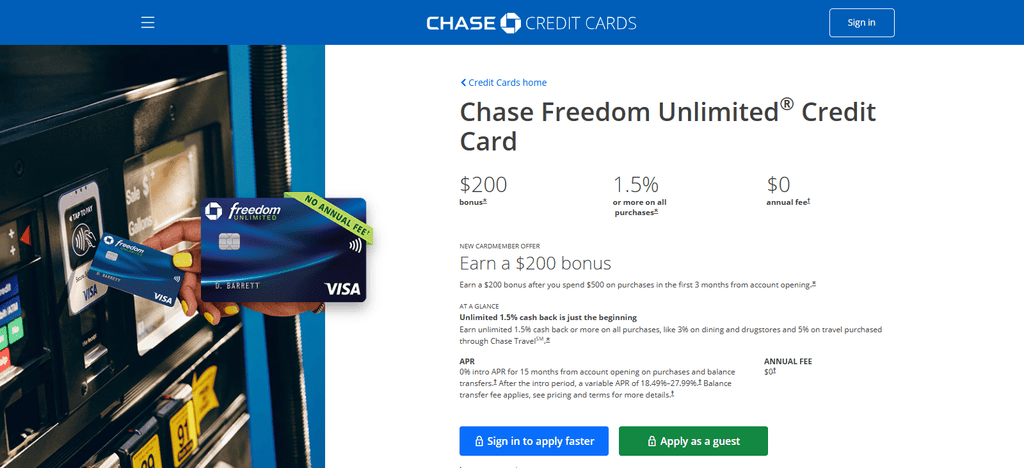
In general, you’ll want a good credit score to be approved, but everyone’s qualifications are different. Variable APR applies to balances carried outside of installment plans. BNPL options allow you to manage cash flow without sacrificing rewards earnings.
However, managing payments responsibly is still important for keeping your account in good health, since missed payments can result in penalty fees and potentially damage your credit score.
Key Features
- Everyday Cashback: Unlimited 1.5% cashback on eligible everyday purchases.
- Bonus categories – Earn more cash back on eligible dining, drugstore and Chase Travel purchases.
- No Annual fee: Removes the annual card fee.
- Introductory APR: Offers an introductory 0% APR on qualifying purchases and balance transfers under existing terms.
- Simple Rewards: Simple cash back, no quarterly category activation required.
Major Limitations
- Variable Regular APR: After the introductory period, interest can be expensive.
- Foreign Transaction Fees: Purchases made internationally may incur extra fees.
- Lower Base Cashback: General purchases don’t earn as much as some category-specific cashback cards.
- BNPL Compatibility: Not all installment providers will take the card for purchases or repayments
3. Chase Freedom Flex®3.
The Chase Freedom Flex® gives you rotating bonus cash back categories and access to Chase Pay Over Time plans. Cardholders can finance eligible purchases over several months and keep earning rewards. The card has no annual fee, making it even more appealing to use for everyday spending. Approval usually requires you to have good credit.
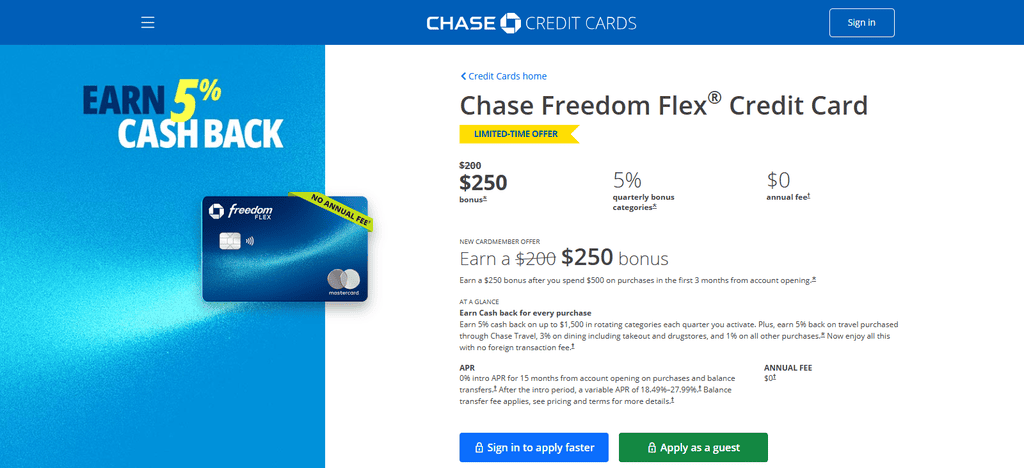
Unpaid revolving balances are charged standard purchase APR, whereas BNPL plans offer structured repayment options. Payment flexibility lets users budget for bigger expenses. It’s important to pay on time, since late or missed payments can result in fees and negatively impact your credit.
Key Features
- Rotating Cashback: 5% cash back in quarterly bonus categories (limit applies, after activation)
- Dining Rewards: Earn 3% cash back on eligible dining purchases.
- Drugstore Rewards: 3% back on eligible drugstore purchases.
- Travel Cashback: Earn 5% cashback on eligible travel booked through Chase Travel.
- No Annual Fee: Earn cashback and never pay an annual membership fee.
Major Drawbacks
- Spending Cap: The 5% rotating-category rate is available only on the quarterly purchase limit.
- Quarterly Activation: Eligible rotating categories will require cardholders to activate when prompted.
- General Rate: 1% cashback for all other eligible purchases.
- BNPL Eligibility: Purchases made with installment providers may not be eligible to receive expected bonus rewards
4. Citi® Double Cash Card
The Citi Double Cash® Card is popular for its simple cash back rewards and Citi Flex Pay option. For eligible purchases, you can choose a fixed monthly payment plan, so you’ll always know when you’re done paying. There’s no annual fee, so it’s a good practical choice for consumers who want simple rewards and the flexibility of BNPL.
Applicants typically need good or excellent credit. Variable APR applies to balances not in a Flex Pay arrangement. As a cardholder, you can still earn rewards on eligible purchases when using installment plans. Paying bills on time, every time can help reinforce good credit behavior, while late payments can result in fees and possibly lower credit scores.
Key Features
- Up to 2% Cashback: Earns 1% on eligible purchases, plus an additional 1% as eligible purchase balances are paid off.
- No Annual Fee: Keeps ongoing costs of card ownership down.
- Simple Rewards Structure: No rotating categories or quarterly activation required.
- Daily Spending: Works for a wide range of eligible purchases.
- Redemption Options: Citi options to redeem cashback rewards that are available under current terms.
Major Limitations
- Payment-Based Rewards: The second part of the cashback is based on paying for qualifying purchases.
- Interest Charges: Having a balance could reduce or eliminate the benefits of rewards.
- Balance Transfer Limitations: Balance transfers usually do not earn purchase cashback.
- BNPL Restrictions: Some installment purchases may not qualify for rewards or acceptance
5. Citi Custom Cash® Card
The Citi Custom Cash® Card earns automatic rewards in the cardholder’s top eligible category, each billing cycle. Citi Flex Pay compatibility. This combo allows users to enjoy higher cash back while splitting larger purchases into fixed monthly payments. The card has no annual fee and is ideal for consumers looking for flexibility and rewards.
Most of the time you need a solid credit profile for approval. The APR will be based on your creditworthiness and also on general market conditions. Flex Pay can be used responsibly to help with budgeting. Fees and credit performance can be affected by missed payments, so careful account management is crucial.
Key Features
- Automatic Bonus Category: Earn 5% cash back in the top eligible spending category each billing cycle.
- Monthly Spending Cap: The 5% rate is only on the first $500 of purchases each month in the category that qualifies.
- Other Purchase Rewards Earn 1% cash back on other eligible purchases.
- No Annual Fee – No regular annual card charge.
- Flexible Spending Categories: May be useful for users who spend a lot in a specific eligible category.
Main Limitations
- Monthly Bonus Cap: Purchases above the qualifying $500 threshold generally get a lower rate.
- Category Limitations: The 5% rate will be given only to eligible categories.
Variable APR: Interest could outweigh the value of the cash back if you carry a balance. - BNPL Reward Uncertainty: Direct purchases and third-party installment transactions could be classified differently
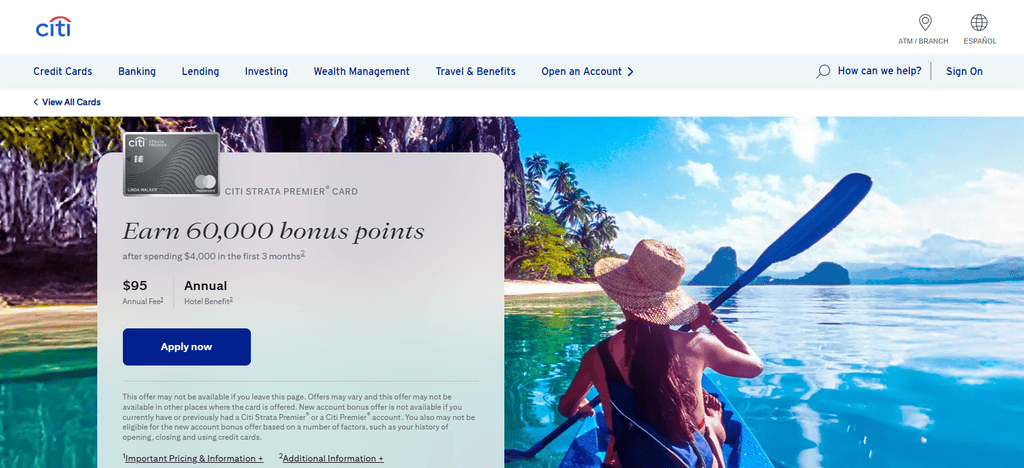
6. Citi® Strata SM Premier Card
If you’re a traveler or rewards enthusiast looking for flexibility to fund larger purchases, then the Citi Strata Premier℠ Card is for you. Eligible transactions can be converted to structured installment payments with predictable costs using Citi Flex Pay. The card has an annual fee but provides good opportunities for travel-related rewards.
Generally, good or excellent credit is needed to be approved. Variable APR applies to balances outside payment plans. BNPL compatibility helps manage travel expenses, electronics, and other large purchases. Making your payments on time helps you maintain a positive account standing, but making them late can lead to fees and a negative credit report.
Key Functions
- Travel Rewards: Earns points on eligible travel purchases.
-Dining Rewards: Earn bonus points on eligible restaurant purchases. - Daily Spending: Earn rewards on eligible grocery and gas buys.
- Points Redemption: Redeem your points for any of the available Citi rewards options.
- Travel-Focused Benefits: Can be attractive to consumers who frequently spend on travel and everyday categories.
Important Constraints
- Annual Fee: Typically has a $95 annual fee.
- Interest Costs: Rewards may be reduced in total value by outstanding balances.
Bonus earning and redemption are subject to eligible transactions and current terms. - BNPL Compatibility: Some providers may restrict credit card funding or disallow certain transactions.7. American Express® Gold Card
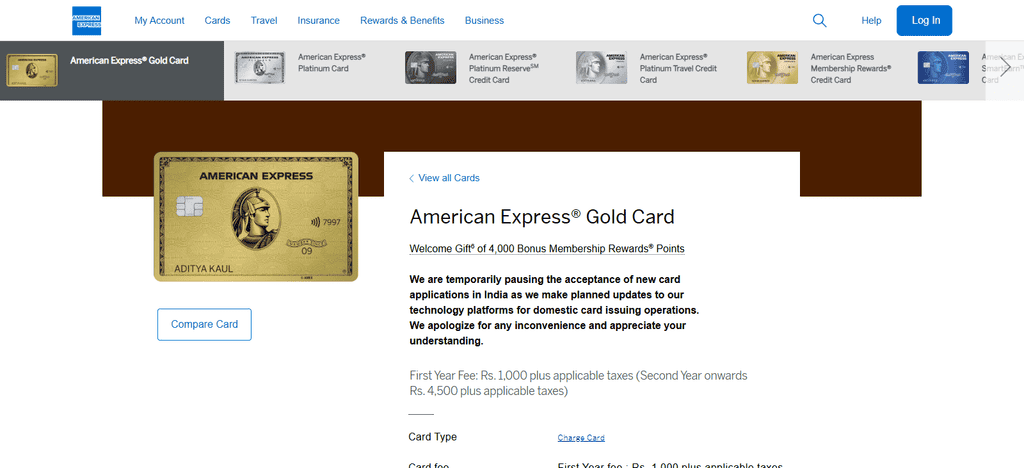
7. American Express® Gold Card
The American Express® Gold Card offers great rewards on dining and grocery purchases and includes the Plan It® feature for installment payments. Eligible purchases can be broken down into fixed monthly payments for enhanced financial flexibility for cardholders.
The card comes with an annual fee and is typically geared toward consumers with good to excellent credit profiles. Rewards are also available on qualifying purchases made on installment plans.
The structure of the account determines the payment terms and interest charges. Responsible repayment helps to maintain good credit health. On the flip side, missing or making late payments can result in fees and damage to a consumer’s credit score.
Key Features
- Dining Rewards: 4X points on eligible restaurant purchases with Membership Rewards.
- Grocery Rewards: Receive 4X points on eligible US supermarket purchases, up to specified limits.
- Travel Rewards: Get bonus points on eligible travel purchases.
- Membership Rewards: Points are redeemable in a flexible manner, subject to the terms of the program.
- Dining-Oriented Benefits: May be good for consumers who spend a lot on eligible food.
Major Limitations
- High Annual Fee: There is currently a $325 annual fee per published terms.
- Reward Caps. Certain bonus types have spending limits or eligibility restrictions.
- Interest and Payment Terms: Some balances may accrue interest, depending on the payment arrangement that applies.
- Acceptance of BNPL: Not all merchants/Installment providers accept American Express.
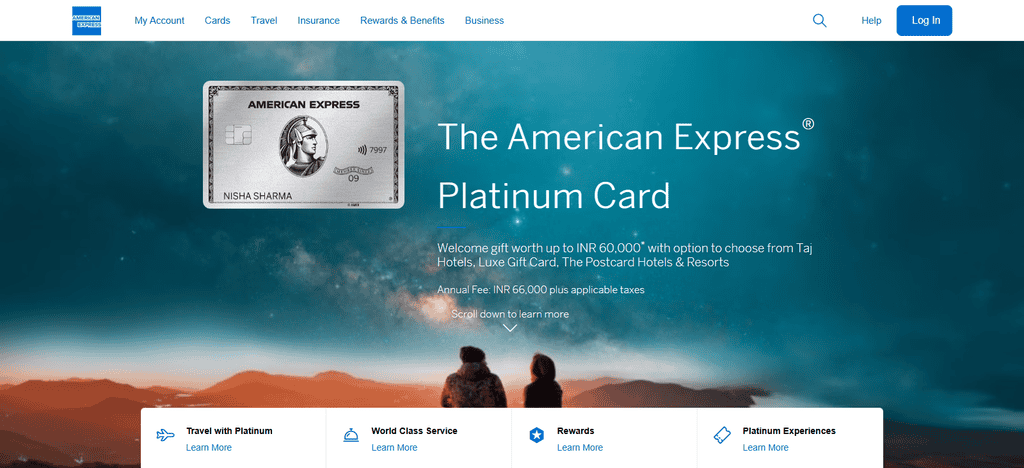
8. The American Express Platinum Card®
The American Express Platinum Card® is a premium travel card, with access to the Plan It® installment payment feature. Eligible purchases can be split into scheduled monthly payments and users can continue to enjoy premium travel perks and rewards. The card has a hefty annual fee, but offers lots of travel perks. Approval generally requires good credit.
Flexible payment can be useful for big purchases such as travel reservations and luxury bills. Installment plans can make budgeting easier, but if you don’t meet your payment commitments, you could be penalized and your credit score could be affected. The key to getting the most out of your card is still using it responsibly.
Key Features
- Premium Travel Rewards: Earns extra Membership Rewards points on eligible prepaid flights and hotel stays.
- Airport Lounge Access: Gives access to participating lounges, subject to eligibility and access rules.
- Travel Benefits: Includes applicable travel protections and services
- Statement Credits: Lists selected credits that may offset costs when their conditions are met.
- Travel Experience: Luxury May suit frequent travelers who enjoy multiple card benefits.
Major Limitations
- High Annual Fee : It carries a significant annual fee, which is $895 at the moment.
- How benefits work: A lot of the credits and perks are earned on eligible purchases as well as how you enrolll or book.
-Low Daily Value: Rewards may not appeal to users who don’t travel frequently. - BNPL Restrictions: Provider and transaction determine the acceptance and eligibility of rewards.
9. The American Express Blue Cash Preferred® Card
The American Express Blue Cash Preferred® Card is a solid cash back card that offers the Plan It® payment option. Cardholders can convert eligible purchases into fixed monthly installments, making it easier to manage household, grocery, and entertainment expenses. The card has an annual fee and you usually need to have good credit to be approved.
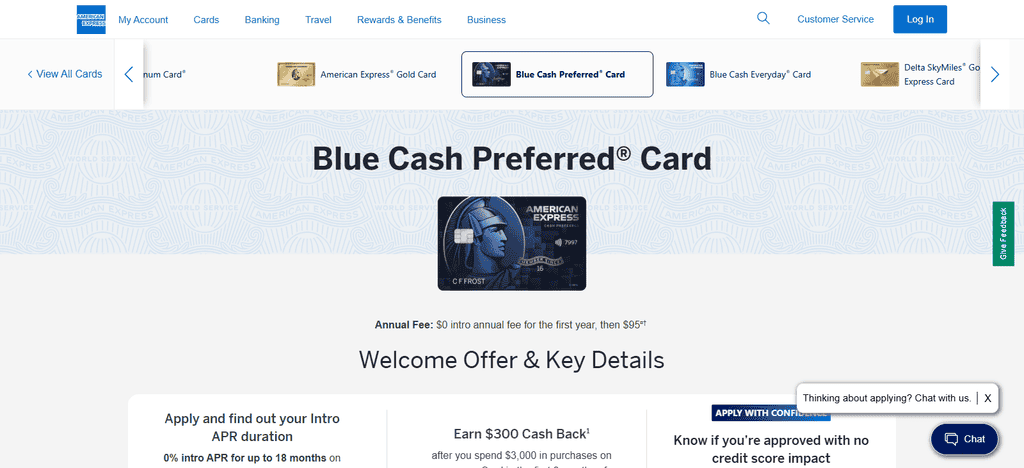
The APR is set by the cardholder’s account terms. Users can still earn rewards and have flexibility of BNPL-like payments. Healthy credit management is supported by regular and timely payments. However, late payments may incur fees and impact your creditworthiness, so developing disciplined repayment habits is essential for long-term financial success.
Core Features
- Grocery Cashback: 6% cashback on eligible US supermarkets up to the annual spending limit.
- Streaming Rewards: Earn 6% cashback on eligible US streaming subscriptions.
- Gas Rewards: Earn 3% back on eligible US gas station purchases.
- Transit Rewards: Earn 3% cash back on eligible transit purchases.
- Introductory Annual Fee: First year annual-fee offer under current terms.
Main Limitations
- Reoccurring Annual Fee: The annual fee is typically $95 after the initial introductory year.
-Spending Caps: Some of the highest reward categories have yearly purchase limits. - US Category Restrictions: Rewards for supermarket and other categories are based on eligible merchant classifications in the US.
- BNPL Reward Uncertainty: Transactions routed through third party providers may not receive the expected cashback rate
10. U.S. Bank Altitude® Go Visa® Signature® Card
The U.S. Bank Altitude® Go Visa Signature® Card is a rewards-focused card that allows installment payment options through U.S. Bank financing features. It provides great value on everyday spending categories while helping users spread the cost of larger purchases over fixed payments.
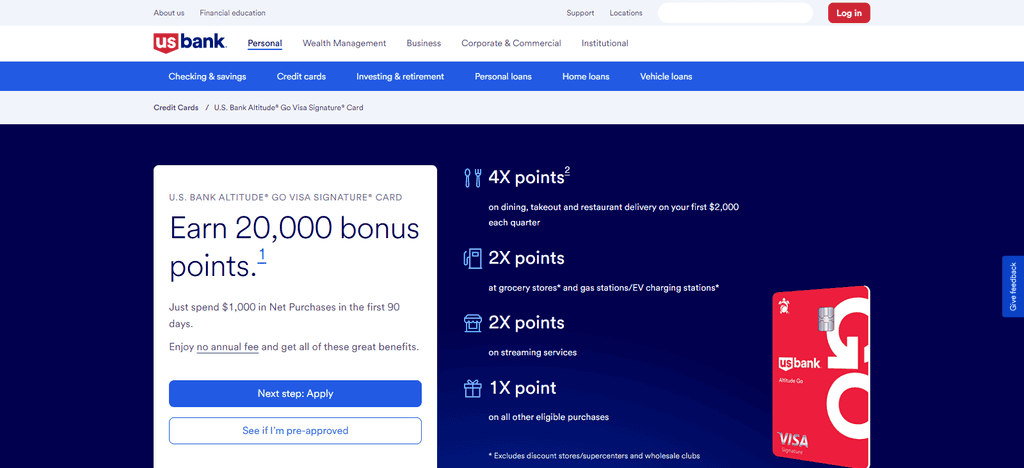
The card has no annual fee, which makes it more accessible to many consumers. In general, good credit is needed to get approved. Variable APR applies to balances not part ofinstallment plans. Flexibility in payment can help with budgeting and expense management. Regular on-time payments are important to maintain good credit health and avoid penalties or negative reporting.
Features
- Dining Rewards: Earn 4X points on eligible dining, takeout and restaurant delivery, subject to limitations.
- Grocery Rewards: Earn 2X points on eligible groceries.
- Gas and EV Rewards: 2X points on eligible purchases at gas stations and EV charging stations.
- Streaming Rewards: 2x points on eligible streaming services.
- No Annual Fee: It provides rewards with no annual fee for an annual card fee.
Major limitations
- Quarterly Dining Cap: The maximum dining rewards rate is only applicable up to the eligible quarterly spend limit.
- Reduced Base Rewards: Most other qualifying purchases will typically earn 1X point.
- Introductory APR End Date: Interest will apply after the promotional period.
- BNPL limitations: You must comply with the payment provider’s installment policy and the transaction’s eligibility.
Conclusion
To put it simply, selecting the right credit card for Buy Now, Pay Later (BNPL) transactions in the USA requires thorough consideration of interest rates, annual fees, cashback offers, repayment options, and credit score criteria. The best card will depend on your spending habits, financial objectives, and ability to make payments on time.
Before you choose a card, check whether your BNPL provider allows credit card payments and any other fees you may incur. Create a realistic budget, keep track of your installment due dates, and avoid unnecessary debt. By comparing your options and borrowing responsibly you can maximize your benefits from your credit card and better manage your payments.
FAQ
What is the best credit card for Buy Now, Pay Later users in the USA?
The best credit card depends on your spending habits, preferred rewards, interest rates, annual fees, and repayment needs. Compare cashback cards, travel rewards cards, and cards offering eligible promotional financing.
Can I use a credit card to pay for BNPL purchases?
Some BNPL providers accept credit cards, while others restrict them or charge additional fees. Check your provider’s payment policies before using a credit card for installments.
Do credit cards offer interest-free payment options?
Some credit cards offer introductory 0% APR promotions or eligible installment plans. These offers have specific terms, and interest may apply after promotional periods end or if conditions are not met.
Can BNPL payments affect my credit score?
Yes. Depending on the provider, BNPL activity may be reported to credit bureaus. Missed payments, reported balances, and credit checks can affect your credit profile differently.