Self-employed Americans may struggle with cash flow management as income can vary month to month while business costs still need to be paid. Freelancers, consultants and independent contractors can take advantage of the right credit card to make necessary purchases, earn rewards and streamline spending.
But you do need to compare introductory apr offers, annual fees, cash back rates, credit limits and repayment terms to find the right card. In this guide, I’ll look at the Best Credit Cards for Self-Employed Cash Flow Management and help business owners make informed financial decisions.
How to Choose the Best Credit Card for Self-Employed Cash Flow Management?
Look for introductory APR deals: Choose cards that provide 0% APR introductory periods for financing short-term purchases. Be aware of promotional periods and redemption deadlines to prevent unexpected interest charges when the regular rates go into effect.
Weigh Annual Fees: Balance annual fees with anticipated rewards and benefits. If you’re self-employed or self-employed, consider no-annual-fee cards for modest spending to keep your business costs down and your profits up.
Look at Rewards and Cashback: Go for cards that reward your regular business spending habits, such as office supplies, advertising, software, and travel. Look for the best cashback rates and spending limits to maximize your bucks.
Review Credit Limits: Set a credit limit that covers necessary business expenses but discourages excessive spending. When you choose your preferred card, consider what you will probably buy, how much you can repay and the possibility of changes in your income.
Features for Managing Expenses: Seek out cards that provide detailed statements, categorization of transactions, controls over employee spending, and reporting tools. These features will help freelancers to track their expenses, organize their records, and make bookkeeping easier.
Familiarize yourself with eligibility requirements: Before you apply, check the credit score requirements, income documentation, and business information requirements. Select cards that match your financial profile to increase your chances of approval and avoid unnecessary applications.
Compare rates and fees Check out regular APRs, balance transfer fees, foreign transaction fees, and late payment fees. Understanding these costs helps the self-employed avoid costly borrowing and protect cash flow.
Align Cards with Business Requirements: Think about your business type, spending habits, stability of income and repayment schedule. Select a card with real benefits and one that doesn’t saddle you with debt you can’t easily pay off with your business income.
Key Points
| Credit Card | Key Point for Cash Flow Management |
|---|---|
| American Express Blue Business Plus® | Earns rewards on everyday business spending and offers an introductory 0% APR period that can help manage short-term cash flow. |
| Ink Business Cash® Credit Card | Combines strong cash back categories with an introductory 0% APR offer, making it useful for covering business expenses during slower revenue periods. |
| Ink Business Unlimited® Credit Card | Provides unlimited flat-rate cash back and an introductory financing period for flexible cash flow management. |
| Capital One Spark Cash Plus | Offers unlimited cash back and high spending capacity, making it suitable for self-employed professionals with significant monthly expenses. |
| American Express Business Gold Card | Rewards common business spending categories and includes expense management tools that help monitor business cash flow. |
| Ink Business Preferred® Credit Card | Strong rewards on travel, advertising, and business services while helping separate business and personal finances. |
| U.S. Bank Triple Cash Rewards Visa® Business Card | Offers cash back on key operating expenses and includes an introductory 0% APR period for business purchases. |
| American Express Blue Business Cash™ Card | Straightforward cash back structure and introductory financing that can support working capital needs. |
| Capital One Spark 1.5% Cash Select | Unlimited flat-rate cash back with no annual fee, making it a practical option for freelancers and sole proprietors. |
| The Business Platinum Card® from American Express | Designed for larger spending needs, offering premium business benefits, expense controls, and flexible payment options. |
1. American Express Blue Business Plus®
The American Express Blue Business Plus® is a good choice for self-employed professionals who want to pay for everyday business purchases without an annual fee. It offers a 0% introductory APR on purchases for 12 months, then a variable APR of 16.99%–28.74%. Earn 2X Membership Rewards points on purchases up to $50,000 per calendar year, then 1X points.
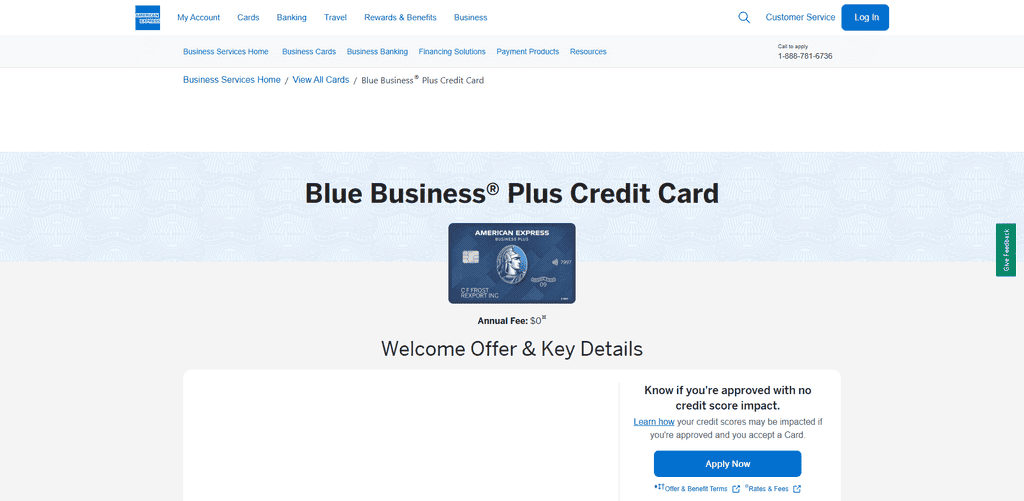
The availability of its credit will depend on the applicant’s financial profile and account history. Tools to manage expenses can help you review your spending . Paying off balances on time also can help you avoid interest charges once the promotional period ends .
2. Ink Business Cash® Credit Card
The Ink Business Cash® Credit Card is a good option for independent workers who want to earn cashback on recurring office and operating expenses. There is no $0 annual fee and an introductory 0% APR for 12 months on purchases and then a variable APR of 16.99%-24.99%. ‘
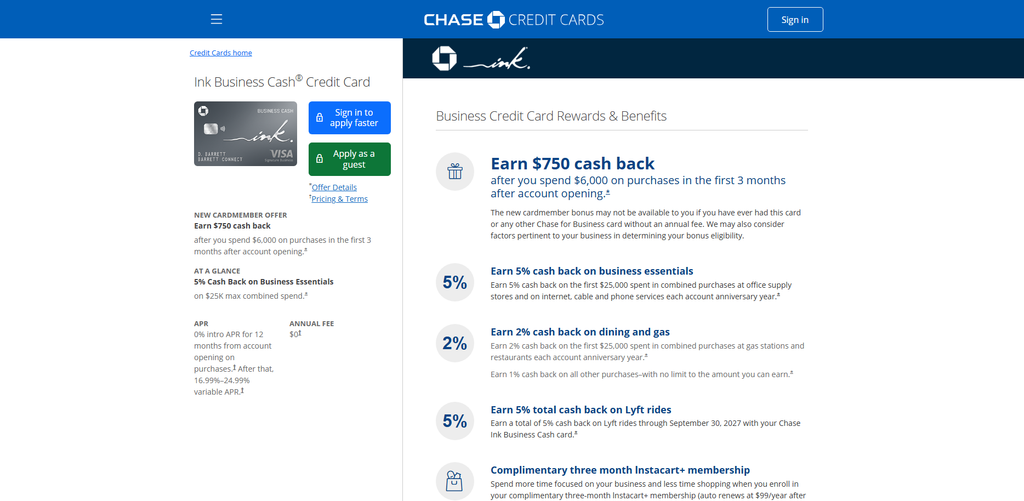
The card earns 5% cash back on eligible office supply store and internet, cable and phone service purchases, up to a combined annual spend cap, as well as rewards in other categories.
Credit limits are subject to approval based on applicant’s creditworthiness. Business statements can be helpful for tracking expenses, and paying on time and checking the ongoing APR can help reduce financing costs.
3. Ink Business Unlimited® Credit Card
If you’re a self-employed American who prefers simple rewards on a range of business expenses, then the Ink Business Unlimited® Credit Card is a good choice. The card has a $0 annual fee. The card has a 0% intro APR on purchases for 12 months (16.99%-24.99% variable APR afterwards).
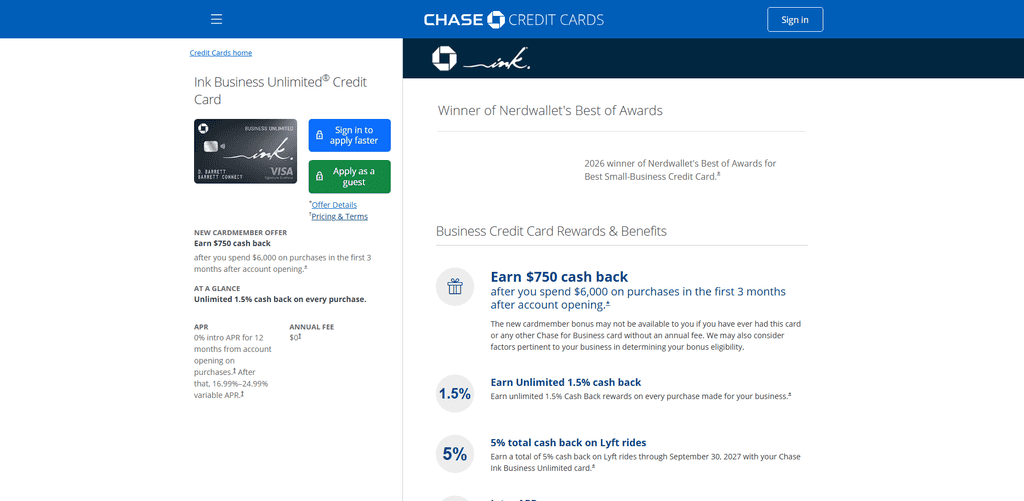
Cardholders earn unlimited 1.5% cashback on qualifying purchases, a benefit that’s good for supplies, software and miscellaneous operating costs. All credit limits are subject to approval and individual financial circumstances.
Monthly statements help you organize your transactions and review your spending. Manage your cash flow by paying off the balance before it accrues interest and not spending more than you expect to make in business income.
4. Capital One Spark Cash Plus
The Capital One Spark Cash Plus is a solid option for self-employed professionals with plenty of business expenses who want steady cashback. It offers an unlimited 2% cashback on eligible purchases, costs $150 a year – but that fee can be made up for by rewards at higher spend levels.
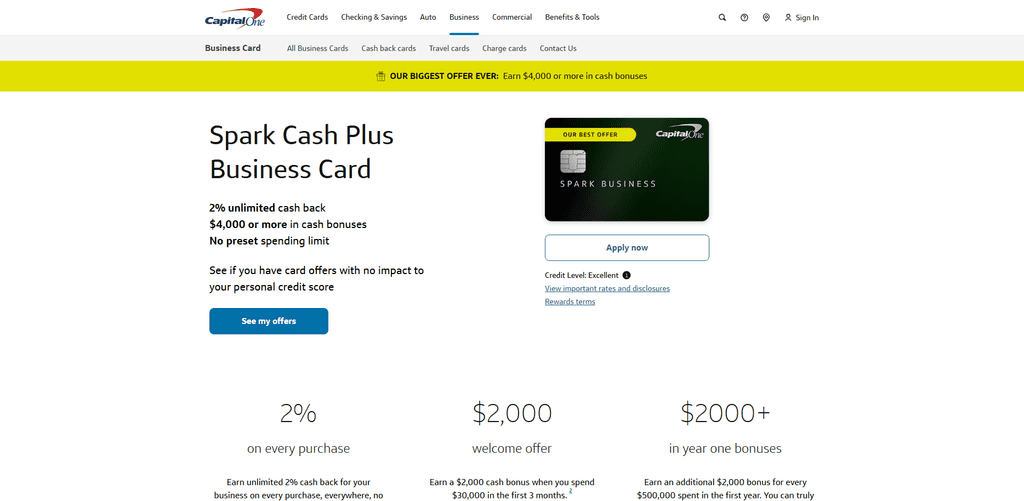
It’s a charge card — not a traditional revolving credit card — so you must pay the full balance each month. That means there’s no standard introductory purchase APR for carrying balances. Your ability to spend can vary with your financial situation and payment history.
Business transaction records help track expenses but applicants need to look into eligibility, payment obligations and fees before applying
5. American Express Business Gold Card
The American Express Business Gold Card is for self-employed owners who spend big in certain business categories. The annual fee is $375, and eligible purchases in the top two qualifying categories earn 4X Membership Rewards points on up to $150,000 in combined purchases each year, then 1X. Eligible categories: advertising, software, restaurants, gas, transit and wireless services.
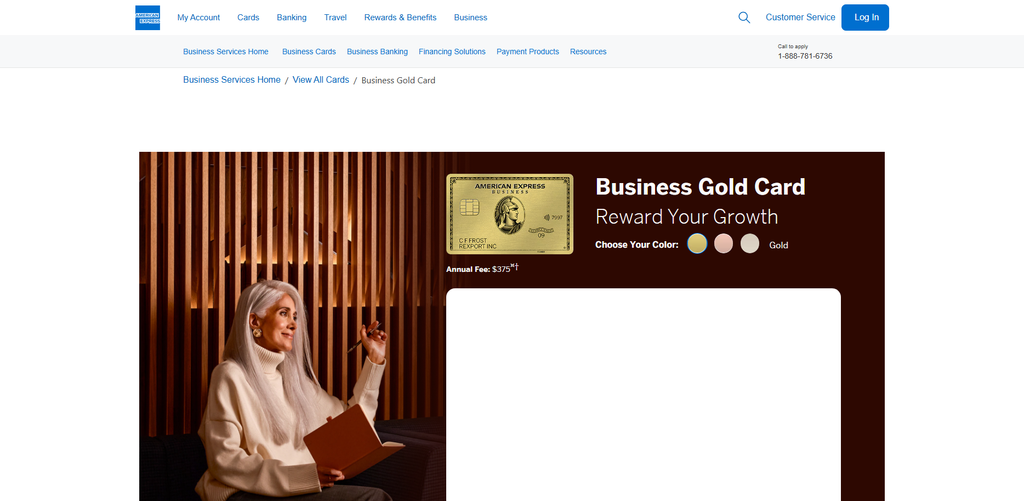
The card does not come with a standard introductory 0% purchase APR; qualifying purchases may be eligible for Pay Over Time terms. Subject to financial circumstances and account history. Credit is subject to status. Review monthly statements and repayment terms to manage financing costs.
6. Ink Business Preferred® Credit Card
If you’re a consultant, freelancer or independent business owner with big spending on travel and select business services, the Ink Business Preferred® Credit Card can be a good fit.
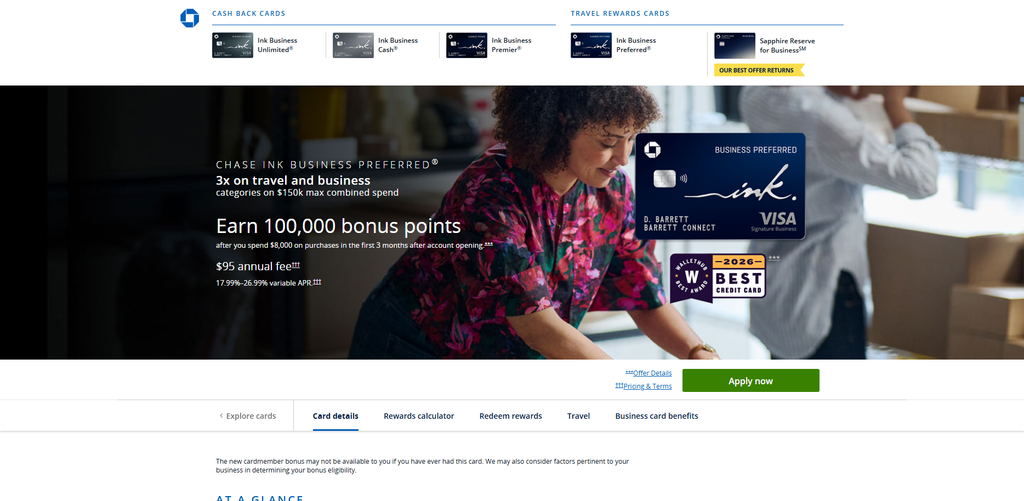
It has a $95 annual fee and earns 3X Chase Ultimate Rewards points on eligible shipping, advertising, internet, cable, phone services and travel purchases, up to the applicable annual spending cap. Other eligible purchases earn 1X points.
Usually it doesn’t have a 0% introductory buy APR, so carrying balances can get expensive. Credit limits subject to approval. Detailed statements will help with expense tracking, and if you manage your balances responsibly, rewards can be used to offset eligible operating expenses.
7. U.S. Bank Triple Cash Rewards Visa® Business Card
Self-employed Americans can get cash back on everyday operating expenses with the U.S. Bank Triple Cash Rewards Visa® Business Card. It has no annual fee and a 0% intro APR on purchases and balance transfers for 12 billing cycles, then the variable APR applies, 16.99%-25.99%, based on your creditworthiness.
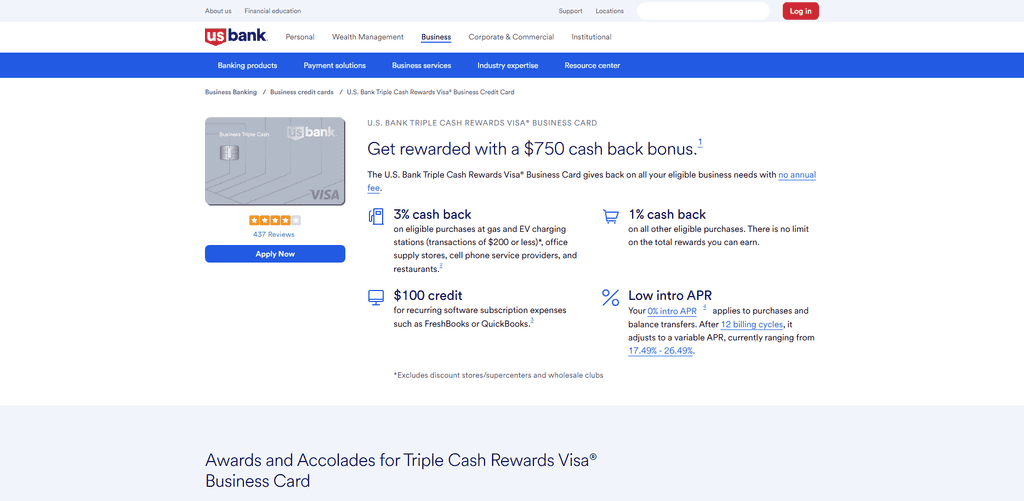
Eligible purchases at gas and EV charging stations, office supply stores, restaurants and cellphone service providers get 3% cashback, while other eligible purchases get 1%. Credit limits subject to underwriting and creditworthiness.
Statements help you organize transactions, and qualifying software purchases may qualify for statement credits. Check transfer fees and post-promotion interest before borrowing.
8. American Express Blue Business Cash™ Card
If you’re a self-employed professional who wants simple cashback and no annual fee, the American Express Blue Business Cash™ Card is a great choice. You’ll enjoy a 0% intro APR on purchases for 12 months, followed by a variable APR ranging from 16.99% to 28.74%. Earn 2% cash back on eligible purchases up to $50,000 per calendar year, then 1%, with cash back automatically credited to the statement.
Credit availability will depend on applicant’s financial profile and account history. Statements and expense management tools help categorize business transactions. Paying the balance in full on time helps preserve cash flow and avoid interest charges after the introductory period.
9. Capital One Spark 1.5% Cash Select
Good for freelancers and independent contractors who want predictable rewards and don’t want to pay an annual fee, the Capital One Spark 1.5% Cash Select Business Card is a good choice. You’ll receive unlimited 1.5% cash back on eligible purchases and an intro APR of 0% on purchases for nine months, then a variable APR of 16.99%–26.99%.
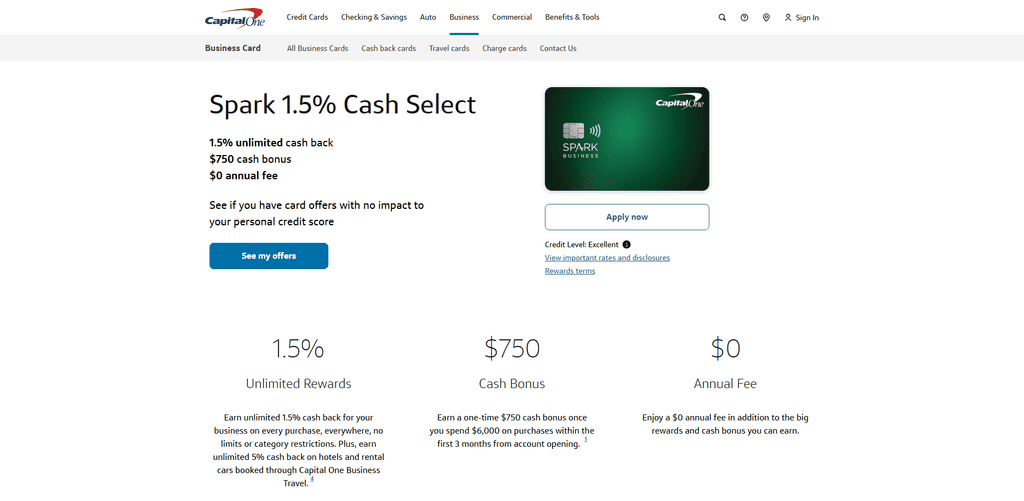
Capital One Business Travel: Book eligible hotels and rental cars for 5% cashback. Subject to credit approval. Restrictions apply. Business statements enable you to monitor purchases and check your monthly expenses. Before the introductory period ends, applicants should check eligibility requirements and plan repayments to avoid unnecessary interest costs.
10. American Express Business Platinum Card®
The Business Platinum Card® from American Express is perfect for self-employed professionals with high travel and business expenses who can justify the premium price. It has a $895 annual fee and offers travel-related rewards and benefits, including 5X Membership Rewards points on eligible flights and prepaid hotels booked through Amex Travel.
It does not provide a typical 0% introductory purchase APR and qualifying Pay Over Time balances have a variable APR of 17.99%–28.74% currently. Spending power is based on payment history and financial circumstances. Expense tools allow you to review your transactions and travel credits can offset fees if you use them all.
Conclusion
Look at introductory APR deals, annual fees, rewards, credit limits and features for tracking expenses to help you choose the best credit card for managing cash flow as a self-employed person. Cards such as the American Express Blue Business Plus, Ink Business Cash and Capital One Spark Cash Plus provide all sorts of perks for paying for your business expenses and earning rewards.
If you’re American and self-employed, you’ll want to find a card that matches your spending habits, your income patterns and your ability to pay it back. Understanding the interest rates, fees and eligibility requirements is just as important. By using credit responsibly, paying off balances on time and tracking expenses, freelancers and business owners can increase their financial flexibility and maintain a healthier cash flow.
FAQ
What is the best credit card for self-employed cash flow management
The best card depends on business expenses, repayment capacity, and rewards preferences. Options include the American Express Blue Business Plus, Ink Business Cash, and Capital One Spark Cash Plus.
Can self-employed individuals qualify for business credit cards?
Yes. Freelancers, independent contractors, consultants, and sole proprietors may qualify. Issuers consider credit history, income, financial circumstances, and application requirements.
Which credit cards offer 0% introductory APR?
Some options include the American Express Blue Business Plus, Ink Business Cash, and Ink Business Unlimited. Promotional periods and eligibility depend on current card terms.
How do credit cards help manage irregular income?
Credit cards can cover eligible business expenses when payments are delayed. However, cardholders should maintain repayment plans and avoid relying on borrowing for ongoing financial shortages.