
Building credit can be tricky when you have little or no borrowing history, especially when so many credit card issuers prefer applicants with existing credit profiles. The good news is there are several credit cards designed to help beginners take their first steps toward better credit.
In this guide, I’ll compare the Best Credit Cards for People With Thin Credit Files based on fees, eligibility requirements, rewards, security deposits, and credit-building features to help you find one that fits your financial needs.
How to Choose the Best Credit Card for a Thin Credit File?
Check eligibility requirements: Pick cards designed for limited credit backgrounds. Check the income requirements, credit checks and approval criteria before you apply, so you don’t waste your time applying unnecessarily and potentially impact your credit profile.
Look at Annual Fees – Look for cards with low or no annual fees. Consider maintenance charges and any other potential costs to ensure your credit-building journey is affordable in the long run.
Compare APR and Interest Rates: Compare purchase APRs before you apply. In general, you can avoid purchase interest and save a lot of money in borrowing costs if you pay your full statement balance by the due date.
Credit Bureau Reporting Check: Look for cards that report payment activity to Experian, Equifax, and TransUnion. This will help you build a credit history when you manage your account responsibly, and the reporting is consistent.
Check Security Deposit Policies: Check out minimum deposit, cap limits and refund terms. Consider a cheap deposit that you can afford, but do not cut the money needed for the basic expenses.
Look at Rewards and Benefits: Look at the cashback, fraud protection, and account management tools. Think about the practical advantages, and don’t pick a card based on rewards that will encourage you to spend more than you should.
Think about Future Upgrade Opportunities: Look for issuers that review accounts for possible unsecured upgrades or refunds of deposits. Responsible payments, low utilization, and consistent account management can help pave the way for future credit opportunities.
Who Should Consider Credit Cards for Thin Credit Files?
First time credit card applicants: First time credit card applicants can use the right options to establish payment history, develop responsible spending habits and build a credit profile.
Young Adults: For young adults with little borrowing history, starter cards that encourage budgeting, on-time payments, and gradually building a better credit history can be helpful.
College Students: Students with limited income and little to no credit history may want to consider eligible student or secured cards to establish credit while managing everyday expenses within affordable limits.
New to the US: Immigrants and newcomers, even with strong financial backgrounds in other countries, might have limited US credit history. They can use the right cards to establish a credit history in the country.
People Who Don’t Borrow Much or Use Credit Cards People who don’t borrow much or use credit cards may have thin files. Responsible use of the card can help generate consistent payment information for credit reporting.
Consumers Rebuilding Financial Independence: Easy cards can be a good way to show you’re financially responsible today if you’re getting back into the game after being out of the credit loop for years by making regular payments and keeping balances in check.
Prospective Loan Applicants: People planning to apply for future car loans, mortgages, or other loans can use credit cards responsibly to build a credit history before submitting their loan applications.
Credit Builders on a Budget: If you can spend wisely and pay balances in full each month, low-fee cards that help you build credit without extra debt or interest are worth looking at.
Key Points
| Credit Card | Key Point |
|---|---|
| Discover it® Secured Credit Card | Reports to all three major credit bureaus and offers cashback rewards while helping new users establish credit history. |
| Capital One Platinum Secured | Requires a refundable security deposit and is designed specifically for consumers with limited or no credit history. |
| Chime Credit Builder Visa® Card | Has no annual fee, no interest charges, and helps build payment history through credit bureau reporting. |
| Petal® 2 Visa Credit Card | Uses cash flow and banking activity in addition to traditional credit data, making approval possible for many newcomers. |
| Capital One Quicksilver Secured Cash Rewards | Provides unlimited cashback on purchases while helping cardholders establish positive credit records. |
| OpenSky® Secured Visa® Credit Card | Does not require a credit check during application, making it accessible for people with very limited credit files. |
| Self Visa® Credit Card | Available through Self’s credit-builder ecosystem and helps users create a consistent payment history. |
| Bank of America® Unlimited Cash Rewards Secured | Offers cashback rewards and reports account activity to major credit bureaus to support credit growth. |
| Citi® Secured Mastercard® | Provides a straightforward path to building credit through responsible usage and on-time payments. |
| Mission Lane Visa® Credit Card | Offers an unsecured credit option for consumers who may not yet qualify for premium credit cards. |
1. Discover it® Secured Credit Card
The Discover it® Secured Credit Card is a secured credit card for people with limited or bad credit history. No minimum credit score required, but approval is dependent on the applicant’s overall financial profile. Annual fee: $0. Refundable security deposit required.
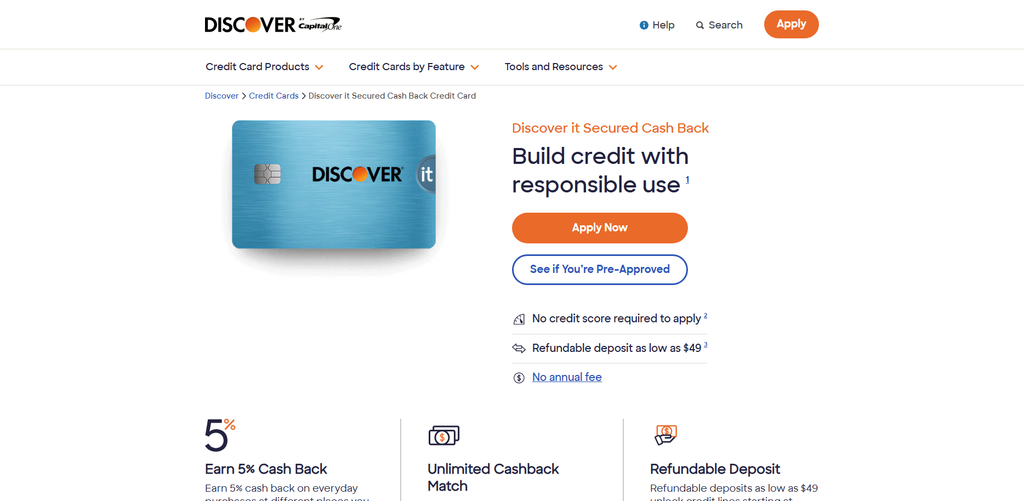
Cash back on purchases is available to eligible cardholders, with rewards based on the terms of the applicable card. Variable purchase APR applies to balances not paid in full. Reports payment activity to the major credit bureaus and may review accounts for an upgrade.
Main Features
- No yearly fee, great for building credit over the long haul.
- Qualified applicants can pay as little as $49 for a refundable security deposit.
- 5% cash back on rotating quarterly categories when you activate (spending cap applies) 1% cash back on all other purchases
- Provides new eligible cardholders with an unlimited dollar-for-dollar match of all cash back rewards earned in the first year.
- Reports payment activity to major credit bureaus and potential upgrade to an unsecured card.
Major Risks
- You have to pay a security deposit that freezes money until you get it back.
- If you carry a balance, the variable purchase APR can be high.
- The quarterly bonus categories must be activated and have spending limits.
- No automatic upgrade or deposit refund implied. Approval not guaranteed
2. Capital One Platinum Secured Credit Card
The Capital One Platinum Secured Credit Card is designed for people who are new to credit or who are rebuilding their credit history. There are no minimum credit score requirements, but approval is based on income, existing debt and creditworthiness.
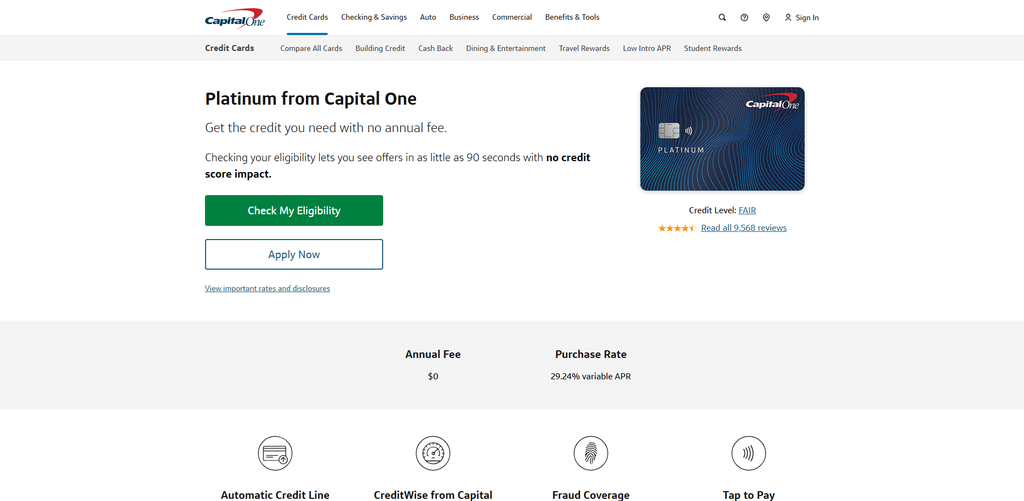
There is no annual fee on the card and a refundable security deposit is required which can be $49, $99 or $200 based on eligibility. The issuer states its purchase APR is variable 28.99%. Making responsible payments can help you build credit and eligible cardholders may receive a higher credit limit or have their deposit refunded
Main Features
- No annual fees.
- Qualified applicants can receive an initial credit line of $200 with a refundable deposit of $49, $99 or $200.
- For those rebuilding or building credit.
- Use responsibly and you may be considered for a higher credit limit without an additional deposit.
- CreditWise gives you the tools to keep an eye on your credit.
Key Risks
- The cash is locked in the security deposit.
- The card does not have a traditional cash-back rewards program.
- Variable APR can be expensive for carrying a balance.
A higher credit limit or return of deposit is not guarantyd and is subject to account review
3. Chime Credit Builder Visa® Card
The Chime Credit Builder Visa® Card is a secured credit building credit card that is perfect for people with limited credit history. There is no credit check or minimum credit score required to apply. There’s no annual fee and no interest under its standard Credit Builder structure.
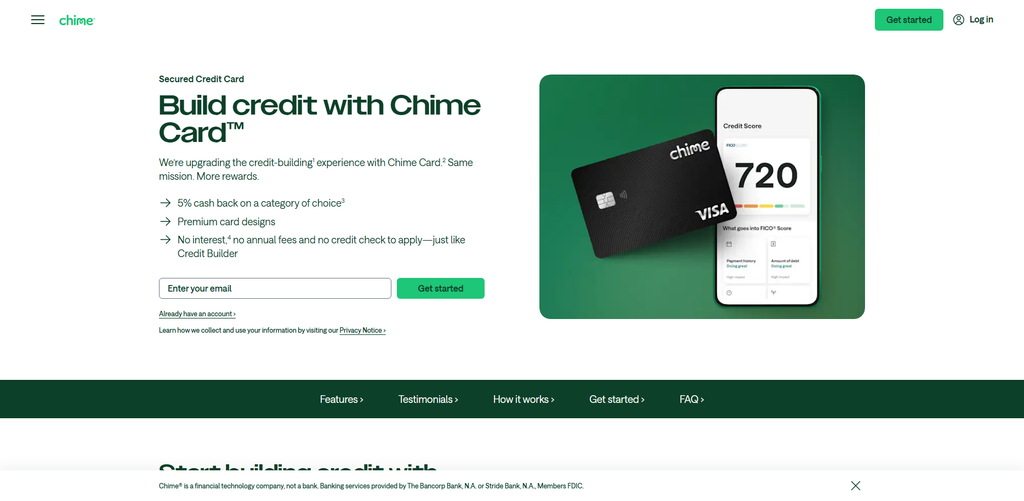
The applicants must establish a qualifying Chime Checking Account and fund the secured account to assist in the spending support. You have a spending limit based on the money you have available, not a credit limit plus a deposit. Users get payment activity reporting to the three major credit bureaus, helping them build payment history.
4. Petal® 2 Visa® Credit Card
The Petal® 2 Visa Credit Card was an unsecured card for those with limited credit history who want to build credit without paying a security deposit. Depending on the application process, other factors like income and banking information may be used to judge applicants as opposed to a traditional credit score.
In the past, the benefits included no annual fee, cash-back rewards and reporting to the major credit bureaus. The applicable offer set the interest rate and other fees.
Make sure that the original Petal 2 card is still accepting applications before publishing current eligibility, fee or APR figures, as Petal’s product lineup and availability may have changed.
Features
- No annual charges.
- There is no traditional credit check needed to apply.
- The standard Credit Builder structure does not charge interest on purchases.
- Users can manage expenses with available funds
- Reports payment activity to major credit bureaus to help with credit building.
Key Risk Factors
- Must have a qualifying Chime account.
- Spending is capped at available funds.
- It is not your normal standard credit limit credit card.
- Improvements to your credit score are not guarantyd and will depend on your overall credit behavior.
5. Capital One Quicksilver Secured Cash Rewards Credit Card
Capital One Quicksilver Secured Cash Rewards Credit Card: secured rewards card for those looking to build credit and earn cash back. There is no fixed minimum credit score for the public, but applicants are approved based on their creditworthiness and financial information.
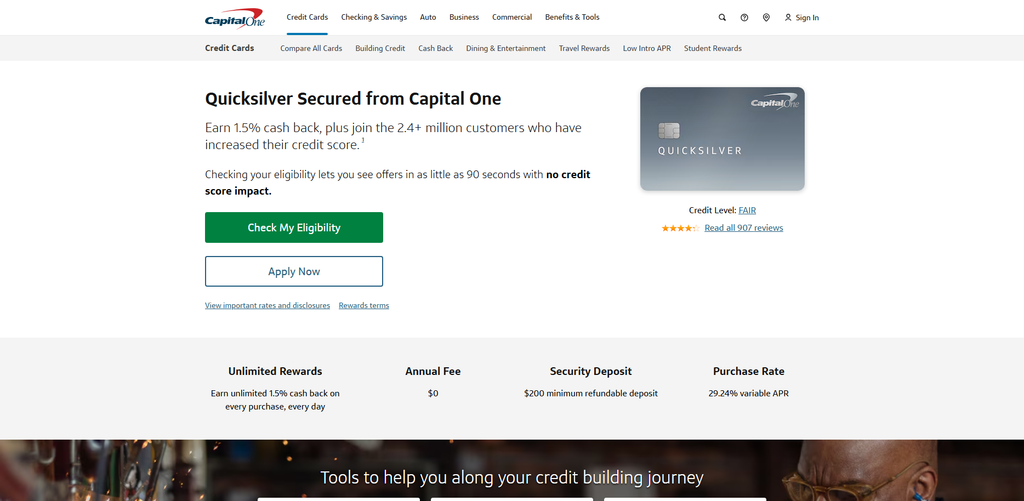
The card has an annual fee of $0 and a refundable security deposit of $200 or more. APR: 28.99% (variable) as of the date of the terms listed. Cardholders will receive 1.5% cash back on eligible purchases. Good management of your accounts can help build your credit history, which may open up opportunities to qualify for an unsecured card.
Main Features
- Cards are unsecured, so generally you don’t need to put down a security deposit.
- Previously had a $0 annual fee.
- For applicants with limited credit history.
- Previously included cashback on eligible purchases.
- A payment history can be established when the account is reported to the major bureaus.
Major Risks
- Check availability of current application and product terms
- There is no guaranty of approval for thin credit file holders.
- APR and other charges may vary based on the particular offer.
- Rewards and fees for the card may vary from those described above
6. OpenSky® Secured Visa® Credit Card
The OpenSky ® Secured Visa ® Credit Card is for consumers with little or no credit history or past credit problems. There is no credit check required to apply, so it’s an option for those who don’t have an established credit score. The card has an annual fee of $35 and needs a refundable security deposit of at least $200 that usually determines your credit limit.
Its listed purchase APR is variable 23.89%. OpenSky reports payment activity to Experian, Equifax and TransUnion, which helps cardholders build credit history. When comparing to other secured cards, applicants should consider the annual fee and deposit.
Features
- No annual fee
- Refundable security deposit, usually starting at $200.
- Get 1.5% cash back on eligible purchases.
- Helps eligible cardholders build credit with responsible account management.
- May provide a path to an unsecured card following account reviews.
Major Risks
- The deposit required locks up money.
- Unpaid balances might be costly because of the variable APR.
- Cash-back rewards can be minimal for low spenders.
- Approval and upgrade to an unsecured card are not guaranteed
7. Self Visa® Credit Card
The Self Visa® Credit Card is a secured credit-building card made for people looking to build or rebuild credit. Applicants aren’t required to undergo a hard credit inquiry, but they do have to meet the eligibility criteria of the issuer. Minimum security deposit is $100. New customers will receive a $0 annual fee for the first year, with the standard annual fee being $25.
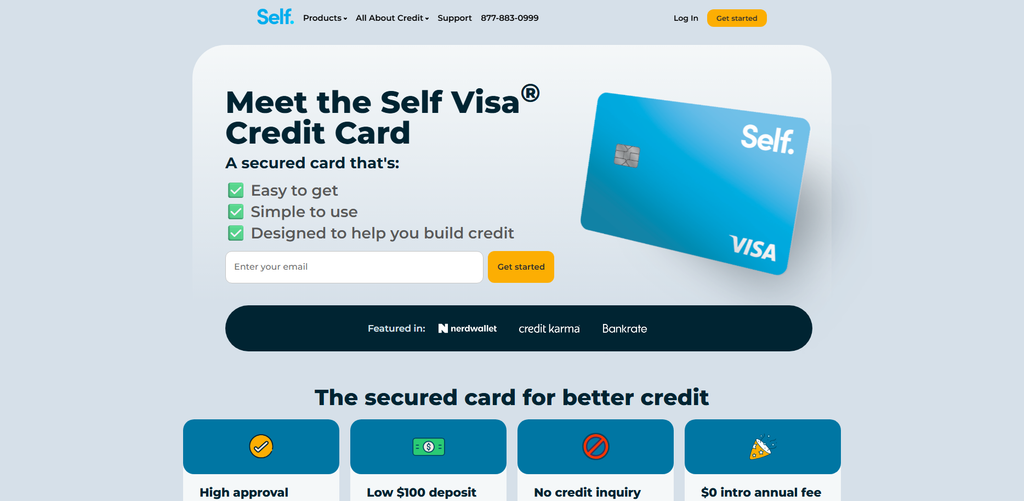
The APR shown is 27.49%. Other fees may apply, such as late-payment or returned-payment fees. For eligible cardholders, the card can help build a payment history, especially when used with responsible spending and regular on-time payments.
Key Features
- No credit check required.
- Ideal for those looking to build or rebuild credit.
- Normally refundable security deposit from $200.
- Reports payment activity to the three major credit bureaus.
- May be available to applicants who have difficulty qualifying for traditional credit cards.
Main Risks
- It costs $35 annually to hold the card.
- The security deposit is non-accessible.
- If balances are not paid in full, interest charges may accrue.
- No credit check doesn’t mean approved or guarantyd credit score improvement
8. Bank of America® Unlimited Cash Rewards Secured Credit Card
The Bank of America® Unlimited Cash Rewards Secured Credit Card is a secured credit card for those looking to build or rebuild their credit. There is no published minimum credit score required for approval. The bank considers the applicant’s creditworthiness, income, and ability to pay back the loan.
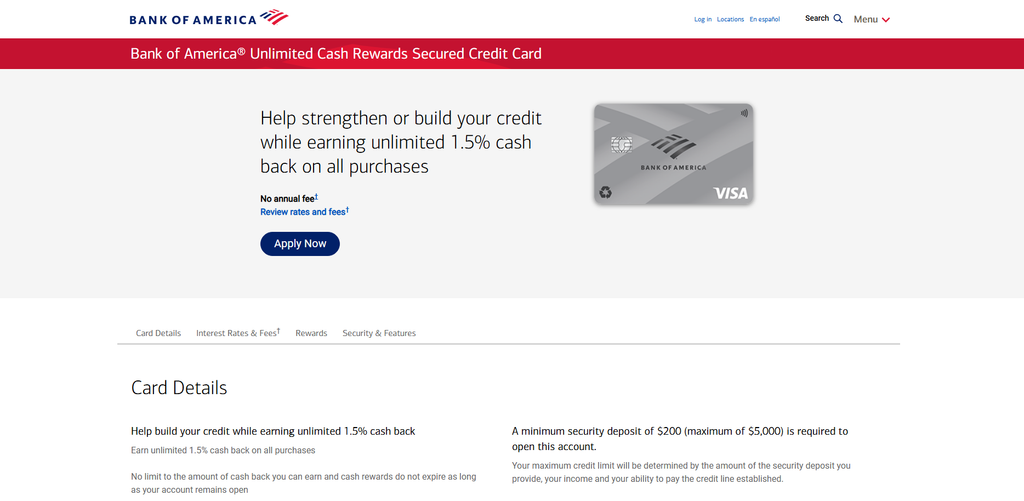
The card has no annual fee but requires a refundable security deposit of $200 – $5,000. Its advertized purchase APR is 27.49% variable. Cardholders receive unlimited 1.5% cash back on purchases. The bank reviews accounts on a periodic basis, and eligible customers may be eligible to receive their security deposit back
The Main Features
- No annual fees.
- Refundable security deposit, typically between $200 and $5,000.
- Rewards accrued as 1.5% cash back on eligible purchases.
- Reports account activity to assist users in building credit history.
- Periodic account reviews may provide an opportunity to regain the deposit.
Major risks
- The first deposit could be enormous.
- Variable APR means revolving balances are expensive.
• Subject to bank approval based on the financial profile of the applicant. - No promise of deposit refunds or advancement to unsecured credit
9. Citi® Secured Mastercard®
The Citi® Secured Mastercard® was created for consumers with limited credit history who want to establish responsible credit habits. Security deposit required to secure line of credit. Subject to Citi’s eligibility and credit review criteria. Applicants should not assume that approval is guarantyd by meeting a certain minimum credit score.
Annual fees, APR and deposit requirements are subject to verification with the card agreement that applies. Generally, secured cards help you build credit if the issuer reports account activity to the major credit bureaus and you make your payments on time. Please check that this card is still available before adding it as an option to apply for, as the products available may have changed.
Features
- Originally designed for applicants with limited or damaged credit histories.
- Backed by a security deposit to secure the line of credit.
- Establishes a traditional card payment system to help develop responsible credit habits.
- Credit reporting can help to build a payment history, when the terms of the account allow for it.
- May be a good fit for users looking for a basic secured-card format without rewards.
Risks Key
- A security deposit is tied up in money.
- Make sure it is available now before you apply.
- Rewards may not be available or limited.
- Interest, fees and eligibility requirements are subject to the applicable card agreement.
10. Mission Lane Visa® Credit Card
The Mission Lane Visa® Credit Card is an unsecured credit card for consumers with limited or less than perfect credit histories. It is also unsecured which means applicants usually do not have to pay a refundable security deposit. Each lender has its own minimum credit score requirements for approval and Mission Lane reviews the application based on their eligibility criteria and financial information.
The annual fee and purchase APR may vary by offer, so be sure to check your specific terms before you apply. If account activity is reported to the big three credit bureaus, the card can help you build a payment history. Important credit-building practices include paying bills on time and maintaining low balances.
Key Features
- Targeted to consumers with poor or no credit history.
- Unsecured cards generally don’t require a security deposit.
- Could make credit available without locking up savings in a deposit.
- Reporting to the major credit bureaus can create a payment history.
- Account reviews may be considered for future credit line opportunities for eligible cardholders.
Key Risk
- Offer may be subject to annual fees.
- Purchase APR may be high.
• The issuer’s discretion to approve and extend credit limits. - Late, high & missed payments can hurt your credit history.
Conclusion
The best credit card for a thin credit file will depend on your financial position, eligibility and credit-building aims. Secured cards, for example, can be a good choice, and some unsecured cards might be appropriate for applicants who want to build credit without paying a deposit. Before applying, compare annual fee, APR, security deposit requirements, rewards and credit bureau reporting.
Look for cards that report to all three credit bureaus and have reasonable terms. Paying your bills on time, keeping your balances low and not applying for credit you don’t need can all help build a stronger credit profile. But the most important thing for a solid credit history is responsible card management, not rewards.
FAQ
What is a thin credit file?
A thin credit file means you have limited credit history, often because you have few credit cards or loans. This can make it harder for lenders to assess your creditworthiness.
Which credit card is best for people with thin credit files?
The best option depends on your eligibility, budget, and goals. Secured cards may suit beginners, while eligible applicants may prefer unsecured cards that do not require a security deposit.
Can I get a credit card with no credit history?
Yes. Some secured and credit-building cards accept applicants with limited or no credit history. Approval depends on the issuer’s requirements, income, and other financial factors.
Do secured credit cards help build credit?
Yes, secured cards can help establish credit when the issuer reports account activity to credit bureaus. Making payments on time and keeping balances low can support positive credit history.